
If you want a quick answer, here are the top VA loan lenders offering the best rates in May 2026:
| Lender | Best For | Notable Rate/Perk |
|---|---|---|
| Navy Federal Credit Union | Overall low rates | 30-yr as low as 5.500%; top 10 VA lender by volume |
| Veterans United | Customer service | Free credit counseling for score improvement |
| USAA | Jumbo loans | Up to $3M; $0 origination fee |
| Guild Mortgage | Low credit scores | Accepts 540+ credit score |
| PenFed Credit Union | Credit union rates | Rates priced lower than major national lenders |
| First Federal Bank | Down payment help | Up to $10,000 in assistance |
As of May 2026, the national average 30-year VA mortgage rate sits at 6.63% — but the right lender can get you significantly below that number.
VA loans are backed by the U.S. Department of Veterans Affairs and come with powerful benefits most borrowers don’t fully use:
- No down payment required
- No private mortgage insurance (PMI)
- Rates typically lower than conventional loans
- Seller can contribute up to 4% toward closing costs
- No prepayment penalty
The problem? Not all VA lenders are equal. Rates, fees, and credit requirements vary widely — and even a small rate difference adds up fast. A 1% difference on a $350,000 loan can mean over $200 more per month and tens of thousands extra over the life of the loan.
This guide cuts through the noise so you can find the lender that fits your situation.
I’m Larry Fowler, publisher of the USMilitary.com Network and a longtime advocate for veteran financial benefits — helping service members navigate options like the best VA loan lenders that offer the best rates has been central to my work since 2007. In the sections ahead, I’ll break down exactly which lenders stand out in May 2026 and how to make sure you’re getting the deal you’ve earned.
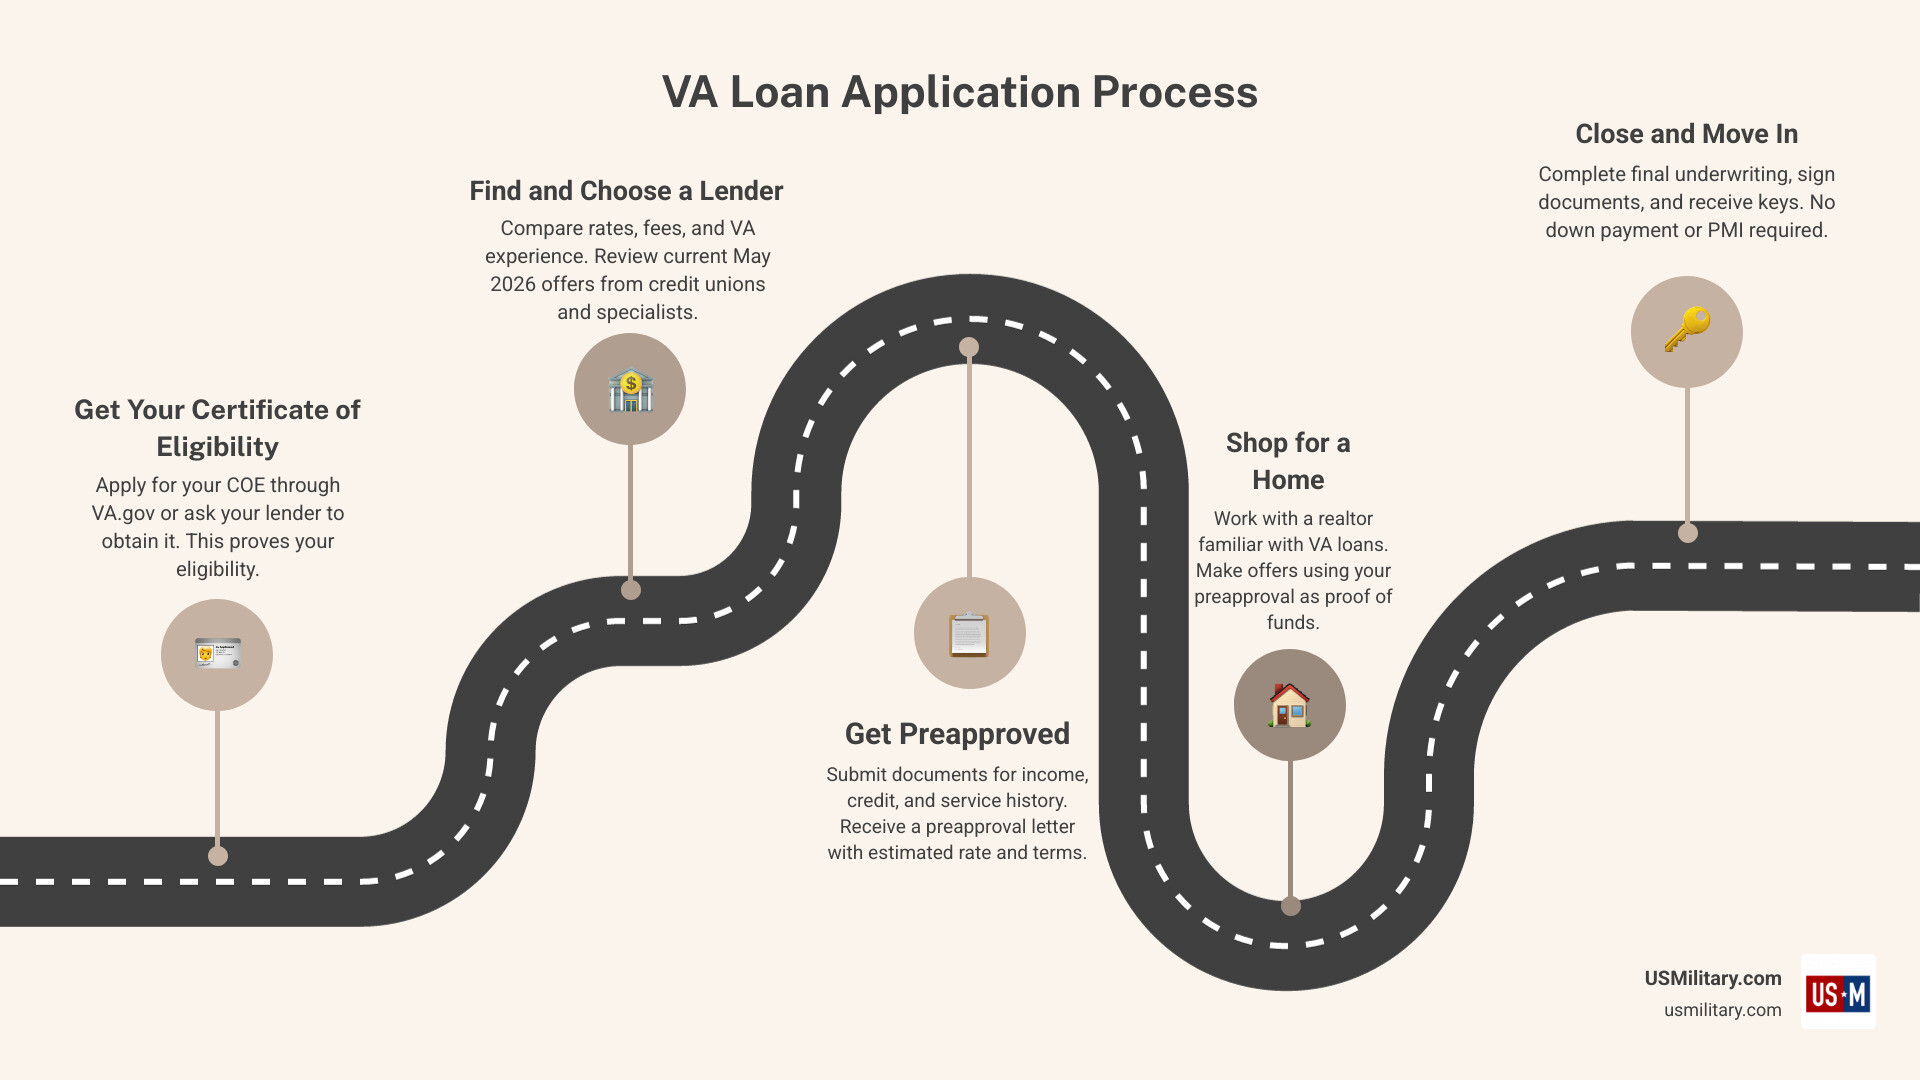
Top VA Loan Lenders That Offer the Best Rates in May 2026
When we look at the landscape of home loans for military in May 2026, the competition among lenders is fierce. While the Department of Veterans Affairs sets the rules for who qualifies, they don’t set the interest rates. That is left to private institutions, which is why shopping around is the single most important thing you can do.
In our research, we’ve found that the best va loan lenders that offers the best rates generally fall into three categories: military-focused credit unions, specialized VA mortgage companies, and national banks.
Military-Focused Credit Unions
Credit unions like Navy Federal and PenFed often lead the pack. Because they are member-owned, not-for-profit organizations, they frequently return their “profits” to members in the form of lower interest rates and reduced fees. In 2025, Navy Federal was a top 10 VA lender by volume, and they continue that momentum in May 2026 by offering 30-year fixed rates as low as 5.500% (with discount points).
Specialized VA Mortgage Companies
Lenders like Veterans United focus almost exclusively on the veteran community. While their base rates are competitive, their real value lies in their understanding of the military lifestyle—handling things like BAH (Basic Allowance for Housing) income and Permanent Change of Station (PCS) orders with ease. They also provide unique resources, like credit consulting, to help you qualify for those top-tier rates.
National Banks with Veteran Programs
Large institutions like USAA and Chase offer the stability of a national footprint. USAA, for instance, has over a century of experience serving the military and currently offers VA loans up to $3 million. For those who prefer a digital-first experience, lenders like SoFi have entered the arena with “no origination fee” promotions and on-time closing guarantees.
| Lender Category | Avg. Min Credit Score | Key Advantage |
|---|---|---|
| Credit Unions | 600 – 620 | Lowest overall interest rates |
| VA Specialists | 580 – 620 | Expert handling of military income |
| National Banks | 620+ | Large loan limits (Jumbo) |
Best VA Loan Lenders That Offer the Best Rates for Low Credit Scores
A common myth is that you need “perfect” credit to get a VA loan. In reality, the VA itself doesn’t actually set a minimum credit score requirement. However, lenders do. If your score has taken a few hits, you aren’t out of the game.
Guild Mortgage is a standout here, as they have been known to accept borrowers with credit scores as low as 540. They also look at “non-traditional” credit history, such as your track record of paying rent and utilities on time. This is a game-changer for younger service members or those who have avoided debt in the past.
Furthermore, if you are just shy of the score needed for the best rates, Veterans United offers a Lighthouse program—a free credit counseling service that helps you identify and fix errors on your report or build a plan to boost your score. Understanding how VA loans work is the first step toward leveraging these flexible credit requirements.
Best VA Loan Lenders That Offer the Best Rates for Jumbo Loans
For those looking at high-value properties in expensive markets, “Jumbo” VA loans are the answer. In the past, you might have had to put money down if you exceeded local loan limits, but since the Blue Water Navy Vietnam Veterans Act of 2019, those limits have largely been removed for veterans with full entitlement.
USAA is a powerhouse in this category, approving VA loans for up to $3 million. They even offer $0 down payment options for loans under $1.5 million, which is almost unheard of in the conventional mortgage world. If you are looking for top military home loans, checking the Jumbo offerings of these major lenders is essential, as the rates on these high-balance loans can sometimes be even more competitive than standard purchase loans. Visit USAA’s website for VA Loan rates.
Factors Influencing Your VA Mortgage Interest Rate
While we talk about “advertised” rates, the rate you actually receive is tailored to your financial profile. Here is what is moving the needle in May 2026:
- Credit Score Tiers: Even though VA loans are more forgiving, a 740 score will almost always get a better rate than a 640 score. Lenders view higher scores as lower risk.
- The 10-Year Treasury Note: Mortgage rates are not directly set by the Federal Reserve. Instead, they usually follow the yield of the 10-year Treasury note. When bond yields go up, mortgage rates follow.
- Loan Term: A 15-year VA loan typically offers a significantly lower interest rate than a 30-year loan. For example, in May 2026, we see 15-year rates as low as 5.125% compared to 30-year rates at 5.500%.
- Debt-to-Income (DTI) Ratio: The VA is more flexible here than conventional lenders, often allowing a DTI up to 41% (and sometimes higher with compensating factors). However, a lower DTI can still help you secure a better rate with certain lenders.
When comparing a VA loan vs conventional loan, the VA’s government guarantee allows lenders to offer lower rates than they would for a standard borrower with the same credit profile.
Understanding Fees, Points, and Closing Costs
The “interest rate” is only half the story. To find the best va loan lenders that offers the best rates, you have to look at the APR (Annual Percentage Rate), which includes the fees.
The VA Funding Fee
Unless you are exempt (usually due to a service-connected disability), you must pay a VA funding fee. For first-time borrowers with $0 down, this is typically 2.15% of the loan amount. For repeat borrowers, it jumps to 3.3%. The good news? You can roll this fee into the loan so you don’t have to pay it upfront.
Origination Fees and Discount Points
Some lenders, like SoFi and USAA, offer $0 origination fees. Others might charge a 1% fee. You also have the option to “buy down” your rate using discount points. One point typically costs 1% of the loan amount and lowers your interest rate by about 0.25%. This is a great move if you plan to stay in the home for a long time, as you’ll eventually “break even” on the upfront cost.
Seller Concessions
One of the best-kept secrets of the VA loan is the 4% rule. The seller can pay up to 4% of the home’s purchase price toward your “allowable” closing costs, including pre-paid taxes, insurance, and even your VA funding fee. This can literally allow you to walk into a home with zero dollars out of pocket. This is especially helpful for those looking into disabled veteran home loans, where every dollar of savings counts.
Strategies to Secure the Lowest VA Loan Rates
If you want to beat the national average, you need a plan. Here is how we recommend you approach the market in 2026:
- Master the Rate Lock: Rates can change multiple times a day. Once you find a rate you like and have a signed purchase contract, ask your lender to “lock” it. Typical lock periods are 30 to 60 days.
- Compare APR, Not Just Rates: A lender might offer a 5.5% interest rate but charge $10,000 in fees. Another might offer 5.8% with $0 fees. The 5.8% loan might actually be the better deal. Always look at the Loan Estimate (LE) document.
- Check for Assistance: Some lenders, like First Federal Bank, offer up to $10,000 in down payment assistance. Even though the VA loan doesn’t require a down payment, putting money down can lower your monthly payment and potentially reduce your funding fee.
- Refinance Later: If you buy now and rates drop in a year, the VA Interest Rate Reduction Refinance Loan (IRRRL) is one of the easiest refinances in the industry. It requires very little paperwork and often no appraisal. You can learn more about VA loan refinance strategies to see how this works.
Before you start house hunting, make sure you know how to apply for your VA home loan and have your Certificate of Eligibility (COE) ready.
Frequently Asked Questions About VA Mortgages
As of late May 2026, the national average for a 30-year fixed VA purchase loan is approximately 6.63%. However, specialized lenders and credit unions are frequently quoting rates between 5.50% and 6.10% for borrowers with strong credit. Refinance rates are slightly different, with the average 30-year VA refinance sitting around 6.46%. Market volatility remains a factor, so we suggest watching the 10-year Treasury yield for hints on which way rates will move next.
This is a lifetime benefit! You can use it as many times as you want, provided you pay off the previous loan or have remaining entitlement. Some veterans even have two VA loans at once if they move and choose to keep their first home as a rental. If you’ve used your benefit before, you’ll want to check out the details on how many times you can use a VA loan to ensure your entitlement is fully restored.
Absolutely. This is where the savings really ramp up. If you have a service-connected disability rating of 10% or higher, you are exempt from the VA funding fee. For a $400,000 loan, that saves you over $8,000 upfront. Additionally, many states offer significant property tax exemptions for 100% disabled veterans. You can find more details on 100 percent disabled veteran home loans to see what specific grants and waivers you qualify for.
Conclusion
Finding the best va loan lenders that offers the best rates requires a bit of homework, but the payoff is worth it. In May 2026, the market favors the educated borrower. Whether you choose a credit union like Navy Federal for their rock-bottom rates, a specialist like Veterans United for their expert guidance, or a bank like USAA for a high-value Jumbo loan, the key is to compare at least three different offers.
The VA loan is more than just a mortgage—it’s a benefit you earned through your service. Don’t settle for the first rate you’re quoted. Use the resources here at USMilitary.com to stay informed, get your paperwork in order, and secure the home you deserve.
For a deeper dive into specific providers, check out our updated list of the best VA loan lenders and start your journey toward homeownership today.
Free for Service Members & Veterans
Get the military benefits intel no one tells you about.
Weekly updates on VA benefits, pay changes, and money tips — free for service members and veterans.
No spam. Unsubscribe anytime. Your info is never shared.
More Than 90% Of Clients Have Increased Ratings! Why Settle For Less Than You Deserve? Expert Priority Help With Your VA Claim Today! Free Evaluation Call!
The mission of Veteran Services United is to support veterans in filing and winning disability claims by offering expert guidance, advocacy, and personalized assistance. Through dedicated service, Veteran Services United empowers veterans to secure the benefits they have earned, ensuring they receive the care and support they deserve.