The Best Car Loans for Military Members: Top Lenders Compared
Car loans for military members offer real advantages over standard auto financing — lower rates, flexible terms, and legal protections that civilian borrowers simply don’t get.
Here’s a quick look at the top military car loan providers:
| Lender | Best For | Starting APR | Max Loan Amount | Max Term |
|---|---|---|---|---|
| PenFed Credit Union | Large loan amounts | 4.44% | $150,000 | 84 months |
| Navy Federal Credit Union | Long repayment terms | 3.89% | No stated max | 96 months |
| USAA | Older vehicles | 4.89% | No stated max | 84 months |
| Service Credit Union | Refinancing | 4.99% | No stated max | 84 months |
These lenders are all military-focused credit unions. That means they’re not-for-profit, so they tend to pass savings on to members through lower rates and fewer fees.
Not sure which one is right for you? The right choice depends on your loan size, how long you need to repay it, and whether you’re buying new, used, or refinancing.
I’m Larry Fowler, publisher of the USMilitary.com Network, where I’ve spent nearly two decades helping active duty members and veterans navigate financial decisions — including car loans for military borrowers at every stage of service. Read on for a full breakdown of each lender so you can drive away with the best deal possible.
Understanding Car Loans for Military Members
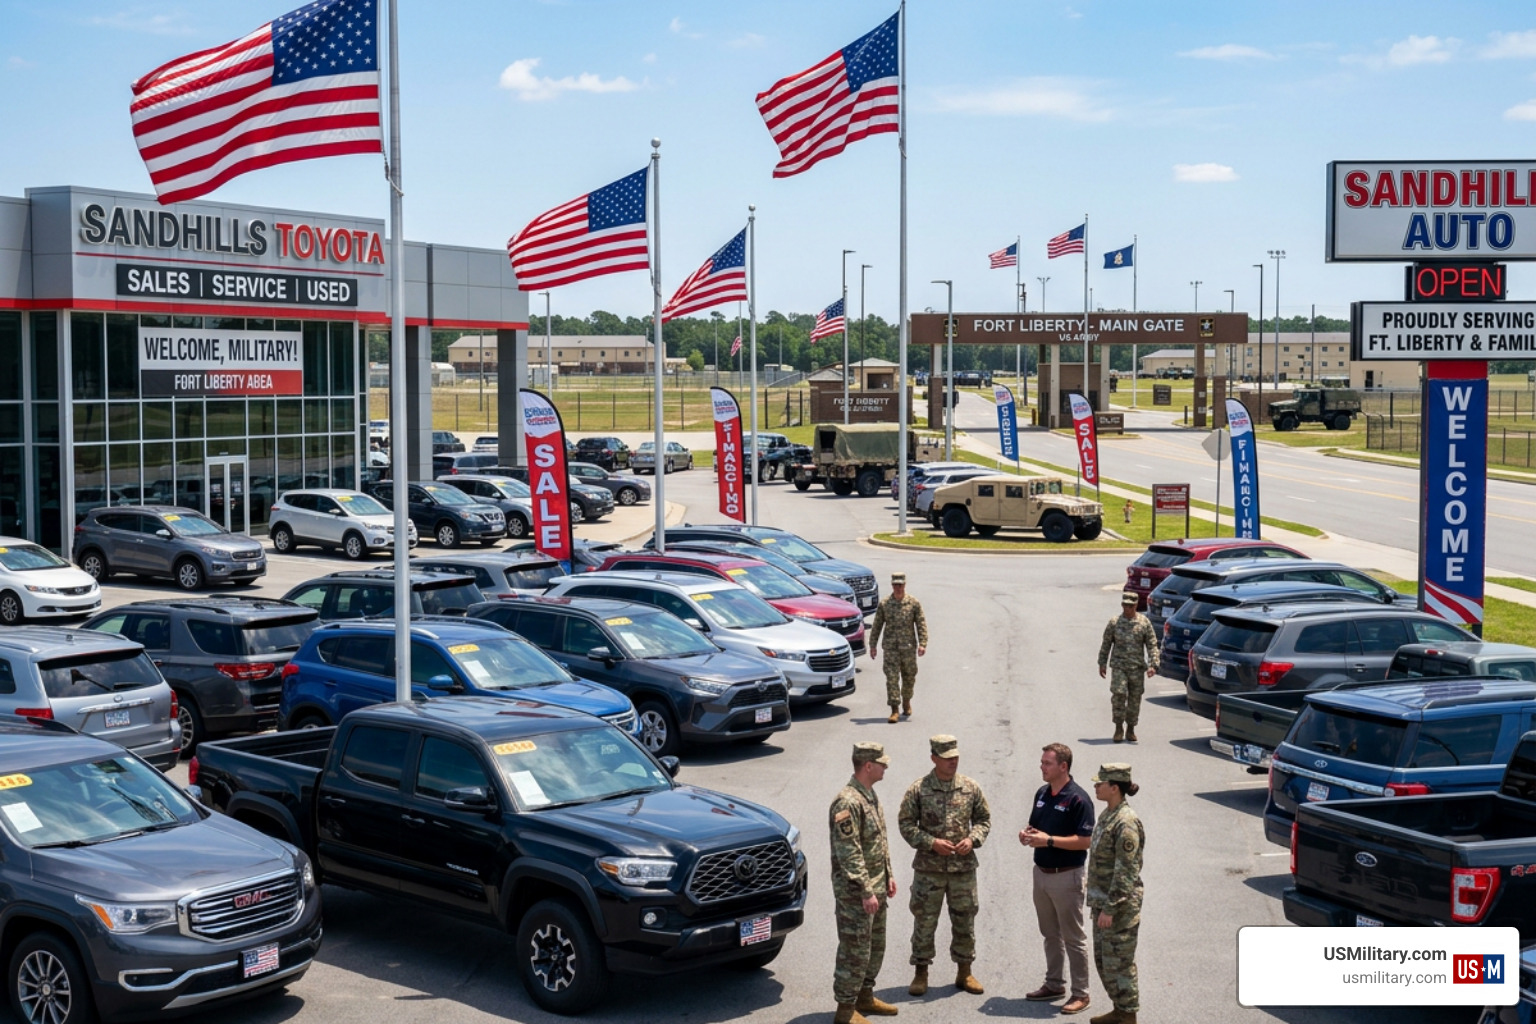
When we talk about car loans for military personnel, we aren’t just talking about a standard bank loan with a flag sticker on the window. These are specialized financial products designed to meet the unique needs of those who serve. Whether you are stationed at a massive installation like Fort Liberty or a remote outpost, your income is stable, but your lifestyle is mobile. Lenders who specialize in the military community understand this.
One of the biggest advantages is the interest rate. Because military members have guaranteed government paychecks, many lenders view them as lower-risk borrowers. This often translates to lower APRs (Annual Percentage Rates) compared to what a civilian with the same credit score might receive. Furthermore, these loans often come with more flexible terms, such as the ability to skip a payment during a deployment or easier paths to military financial protection if your circumstances change.
Membership in a military credit union is often the “secret sauce” here. Unlike big commercial banks, credit unions like Navy Federal or PenFed are member-owned. They don’t have to answer to Wall Street shareholders, which is why they can offer perks like no U.S. domicile requirements. This is huge for service members stationed overseas who need to secure financing for a vehicle they’ll use upon their return or even while abroad. Plus, the processing times are often lightning-fast—sometimes providing an approval decision in just 24 to 48 hours.
Key Differences from Standard Auto Loans
If you walked into a standard dealership today, you might be offered a loan with hidden fees and rigid requirements. Military-specific loans flip the script:
- Lower Fees: Most military lenders eliminate application fees and offer no-penalty early payoffs.
- Lenient Credit Requirements: While credit scores still matter, military lenders often look at the “whole person,” including your service history and rank.
- Unsecured Options: Some specialized programs offer unsecured loans, meaning you don’t necessarily have to use the car as collateral in the same way traditional loans require.
- 125% Financing: Lenders like PenFed allow you to finance up to 125% of the car’s value. This helps cover taxes, registration, and even that extended warranty you’ve been eyeing.
Eligibility for Service Members and Veterans
Who exactly can get these deals? Eligibility is generally broad but specific to your connection to the armed forces. If you are looking at military loans, you usually fall into one of these categories:
- Active Duty: Members of the Army, Navy, Air Force, Marine Corps, Space Force, and Coast Guard.
- National Guard and Reserve: Weekend warriors and activated guardsmen are eligible for the same great rates.
- Retired Veterans: If you’ve put in your 20 years or have a qualifying discharge, you are still part of the family.
- Family Members: Spouses and children of service members can often join these credit unions and access the same auto loan benefits.
Legal Protections and Financial Benefits
Beyond just lower interest rates, we have access to powerful legal shields that civilians don’t. These protections ensure that a sudden deployment or Permanent Change of Station (PCS) move doesn’t ruin your financial life.
The Servicemembers Civil Relief Act (SCRA) is your primary defense. If you took out a car loan before entering active duty, the SCRA mandates that your interest rate be capped at 6%. Additionally, the SCRA protects you from vehicle repossession without a court order, provided you made at least one deposit or payment before your service began.
Another critical protection is the Military Lending Act (MLA). The MLA prevents lenders from charging military members more than a 36% Military Annual Percentage Rate (MAPR), which includes various fees that standard APRs might hide. When you work with the top military-friendly banks, you are choosing institutions that built their entire business model around these legal frameworks.
One of the most practical benefits for those of us on the move is the right to lease termination. Under certain conditions, such as receiving PCS orders for an OCONUS (outside the continental U.S.) location or a deployment of 180 days or more, you can terminate your vehicle lease without paying early termination charges.
Maximizing Your Rate Discounts
Even after you find a low rate, you can often push it even lower. Most military lenders offer “stackable” discounts:
- Autopay Incentives: USAA and others often shave 0.25% off your APR just for setting up automatic monthly payments.
- Direct Deposit Requirements: Service Credit Union offers a significant rate reduction (up to 0.75%) if you have your military pay directly deposited into their accounts.
- Loyalty Bonuses: Some lenders offer $200 bonuses or rate discounts for refinancing an existing loan from a different institution.
Steps to Secure Car Loans for Military Families
We know that military life is a team sport. Spouses are often the ones handling the paperwork while a service member is in the field.
- Verify Spouse Eligibility: Most military credit unions extend full membership to spouses and dependents.
- Joint Applications: Applying together can sometimes help if one partner has a higher credit score, though the military member’s status is what usually triggers the specialized “military” rate.
- Power of Attorney (POA): If the service member is deployed, a specific Power of Attorney is often required for the spouse to sign the loan documents.
Choosing the Right Military Car Loan Provider
Selecting a lender is about more than just finding the lowest number. You need to match the lender’s strengths with your specific car-buying goals.
Considerations for Large Loan Amounts and High Value Vehicles
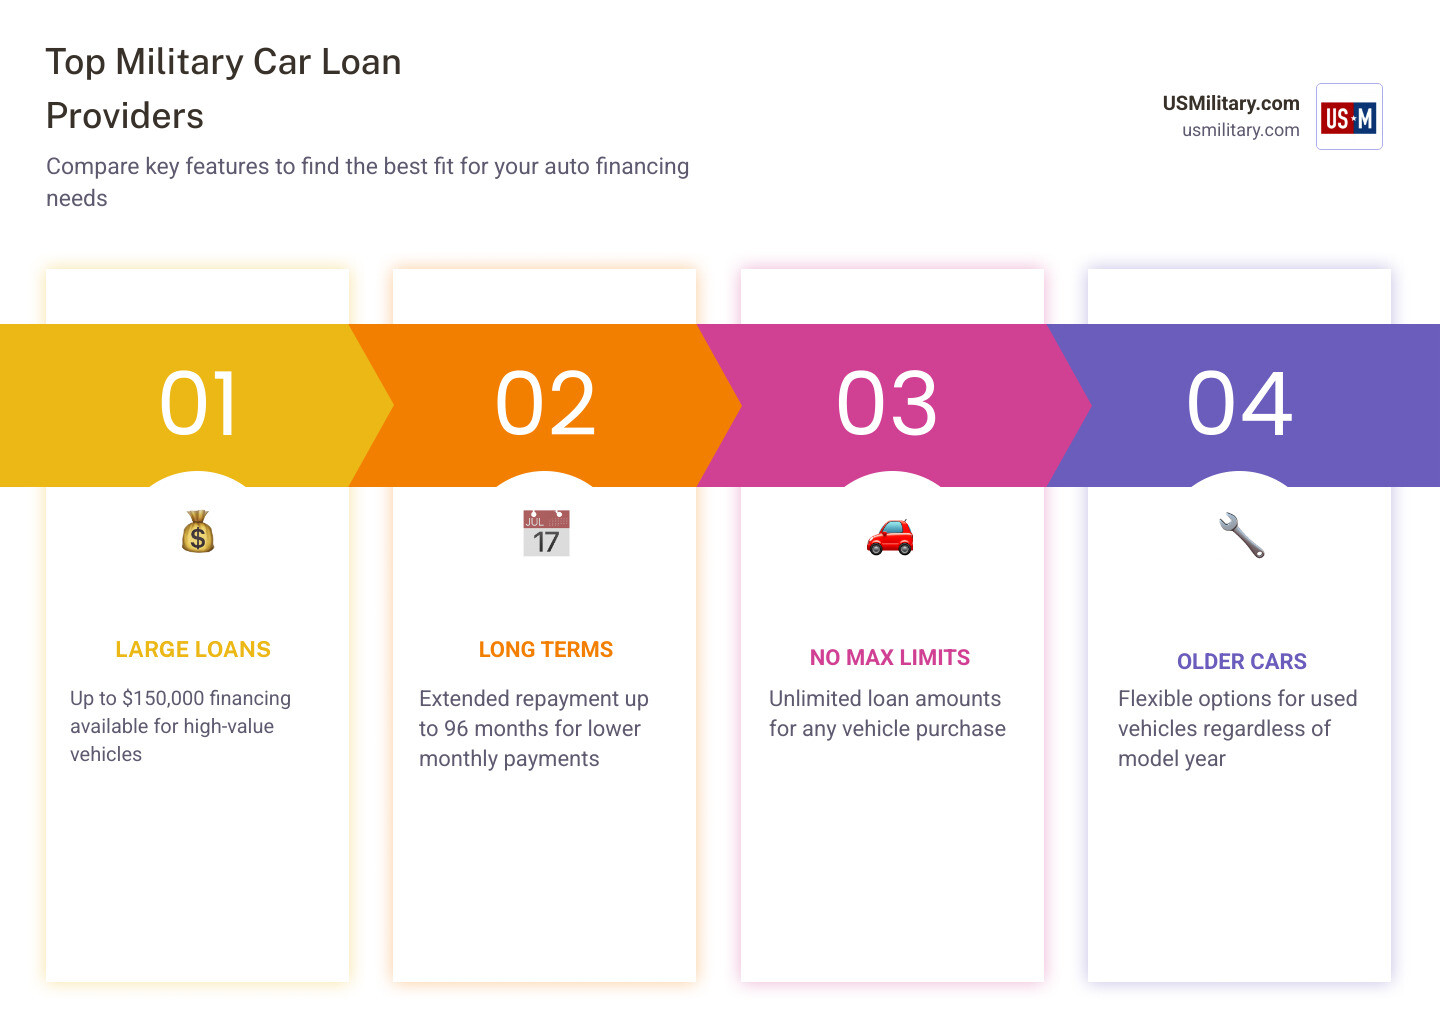
If you’re in the market for a high-end truck or a luxury SUV, PenFed Credit Union is a standout. They offer loan amounts as high as $150,000. Perhaps more importantly, they offer financing up to 125% of the purchased car’s value. This is incredibly helpful if you don’t have a large down payment but want to ensure all your “out-the-door” costs—like title fees and sales tax—are covered in one monthly payment.
Considerations for Longer Repayment Terms and Older Vehicles
Sometimes you need a lower monthly payment, which means stretching out the loan term. Navy Federal Credit Union offers some of the longest terms in the industry—up to 96 months for new vehicles (minimum $30,000 loan). While we generally recommend the shortest term you can afford to save on interest, having that 96-month option can be a lifesaver for your monthly budget.
If you prefer a “classic” or an older used car, USAA is often the best bet. They have specific loan categories for “older cars,” which they define as models from 2017 or earlier. Many traditional banks won’t touch a car that’s more than five or six years old, but USAA will finance them for up to 72 months.
How to Apply for Your Military Auto Loan
The application process for car loans for military members is streamlined but requires specific documentation.
- Check Your Credit: Before applying, grab your free annual credit report. Knowing your score helps you realize which tier of APR you’ll likely land in.
- Gather Your Documents:
- Proof of Service: Usually your military ID or a DD214 for veterans.
- Income Verification: Your most recent Leave and Earnings Statement (LES) is the gold standard here.
- Contact Info: You’ll need a permanent address and often a secondary contact for a family member in case you are deployed.
- Get Preapproved: This is the most important step. A preapproval from Navy Federal, for example, is good for 90 calendar days. This gives you a “blank check” to take to the dealership, turning you into a “cash buyer” in the eyes of the salesman. This gives you massive negotiating leverage.
Critical Considerations Before You Sign
Before you put pen to paper, we need to talk about the “boots on the ground” reality of car ownership in the military.
PCS Moves and Overseas Shipping: If you think there is any chance you will be moved overseas, check the fine print. Some lenders make it very difficult to ship a financed vehicle out of the country. Stick with military-focused lenders like USAA or Navy Federal; they have established processes for issuing the “permission to ship” letters you’ll need at the port.
The 30% APR Trap: Beware of dealerships right outside the base gates. Some of these lots target young E-1s and E-2s with “guaranteed approval” and “$0 down” offers that come with predatory 30% interest rates. On a $26,000 car, a 30% APR loan over 96 months could result in you paying over $62,000 in total. That is a financial anchor that can sink a career. Always secure your financing through a credit union before you step onto a dealer’s lot.
Total Cost of Ownership: A car payment is only one part of the equation. You also need to factor in insurance, fuel, and maintenance.
Frequently Asked Questions about Military Auto Financing
Who qualifies for a military car loan?
Generally, active duty members of all branches, National Guard and Reserve members, retired veterans with an honorable discharge, and their immediate family members (spouses and children) qualify. Some credit unions like PenFed are open to everyone, but they still offer specialized “military-style” benefits.
How does the SCRA protect my auto loan?
The SCRA caps interest rates at 6% for loans taken out before active service. It also prevents lenders from repossessing your vehicle without a court order while you are on active duty, and it allows you to terminate a lease early if you receive PCS orders for an overseas location or a deployment of 180+ days.
Can I get a car loan while stationed overseas?
Yes. Military-focused lenders are very used to this. You can apply online or over the phone from an APO/FPO address. They can often mail the preapproval check to you or directly to a U.S.-based dealership where you plan to pick up the car.
Conclusion
At USMilitary.com, we believe that financial readiness is a key component of overall mission readiness. Securing one of the best car loans for military members isn’t just about saving a few bucks—it’s about protecting your credit, your family’s budget, and your peace of mind.
By choosing a lender that understands the military lifestyle, leveraging the protections of the SCRA, and avoiding the predatory traps found outside the base gates, you can ensure your next vehicle purchase is a victory. Whether you’re buying your first “hoopty” or your dream truck, do your research, get preapproved, and drive away with a deal today.
Free for Service Members & Veterans
Get the military benefits intel no one tells you about.
Weekly updates on VA benefits, pay changes, and money tips — free for service members and veterans.
No spam. Unsubscribe anytime. Your info is never shared.