How to Find a VA Home Realtor Who Protects Your Budget
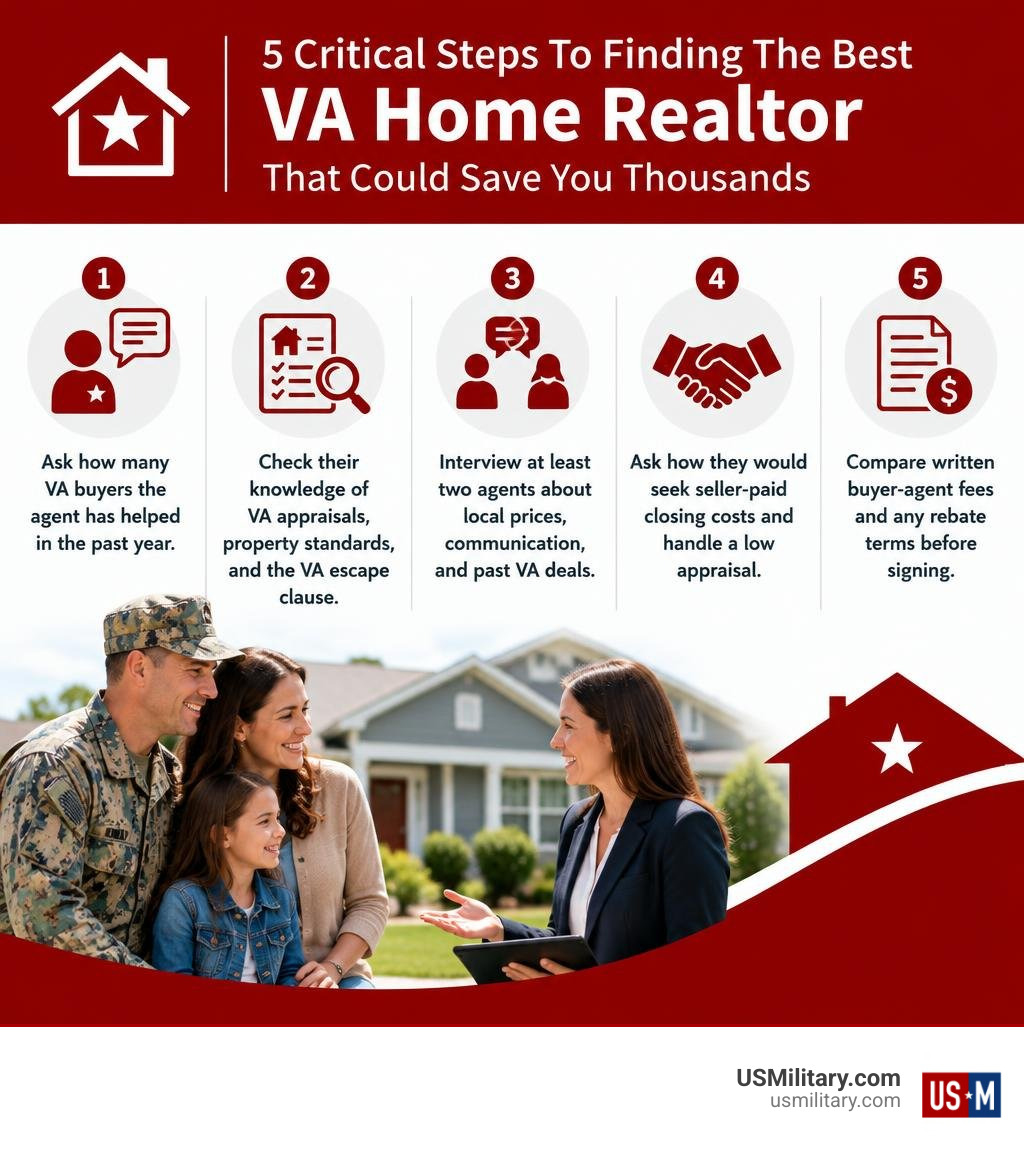
Use these 5 Critical Steps To Finding The Best VA Home Realtor That Could Save You Thousands:
- Ask how many VA buyers the agent has helped in the past year.
- Check their knowledge of VA appraisals, property standards, and the VA escape clause.
- Interview at least two agents about local prices, communication, and past VA deals.
- Ask how they would seek seller-paid closing costs and handle a low appraisal.
- Compare written buyer-agent fees and any rebate terms before signing.
A VA loan may let you buy with no down payment and no private mortgage insurance. But you can still face closing costs, so the right agent should help you spot risks and negotiate terms that fit your budget.
I’m Larry Fowler, a Navy veteran and publisher of USMilitary.com, where I’ve covered military and VA benefits since 2007. In 5 Critical Steps To Finding The Best VA Home Realtor That Could Save You Thousands, I’ll help you turn that guidance into clear questions for your agent search.
Similar topics to 5 Critical Steps To Finding The Best VA Home Realtor That Could Save You Thousands:
- Best VA Lender: New Day USA, Veteran United, Rocket Mortgage, Wholesale United, LoanDepot, or Navy Federal Credit Union
- New Day USA vs Veterans United Home Loan For My VA Home Loan
- The Best VA Home Lenders And Their Best Rates
Understanding the Value of a VA-Specialized Real Estate Agent
Navigating today’s housing market requires more than just searching for open floor plans. With the median price of an existing home in the United States sitting at $429,100, purchasing a home represents one of the largest financial commitments you will make. While conventional loans require down payments of 3% or more alongside recurring private mortgage insurance (PMI), your military service earns you a government-backed mortgage with 0% down and zero monthly PMI.
However, maximizing these benefits starts with understanding your VA home loan eligibility and partnering with a real estate professional who understands Department of Veterans Affairs protocols. Following the nationwide real estate changes where commissions average roughly 5.44%, buyers must sign clear representation agreements. An agent who is well-versed in VA loans ensures you are not paying unnecessary out-of-pocket fees while vigorously representing your interests.
Why You Need The 5 Critical Steps To Finding The Best VA Home Realtor That Could Save You Thousands
A generalist agent might treat your transaction like any conventional sale, which often leads to costly delays or missed savings. An experienced VA realtor protects your earnest money by insisting on the mandatory VA escape clause in your purchase agreement. This clause ensures that if the home does not appraise for the agreed sales price, you can walk away with your full deposit intact.
Furthermore, a knowledgeable representative understands how to negotiate seller concessions up to 4% of the appraised property value. These funds can cover closing costs (which typically range from 3% to 6% of the loan amount), prepay taxes and insurance, or even pay down debt, directly keeping thousands of hard-earned dollars in your bank account.
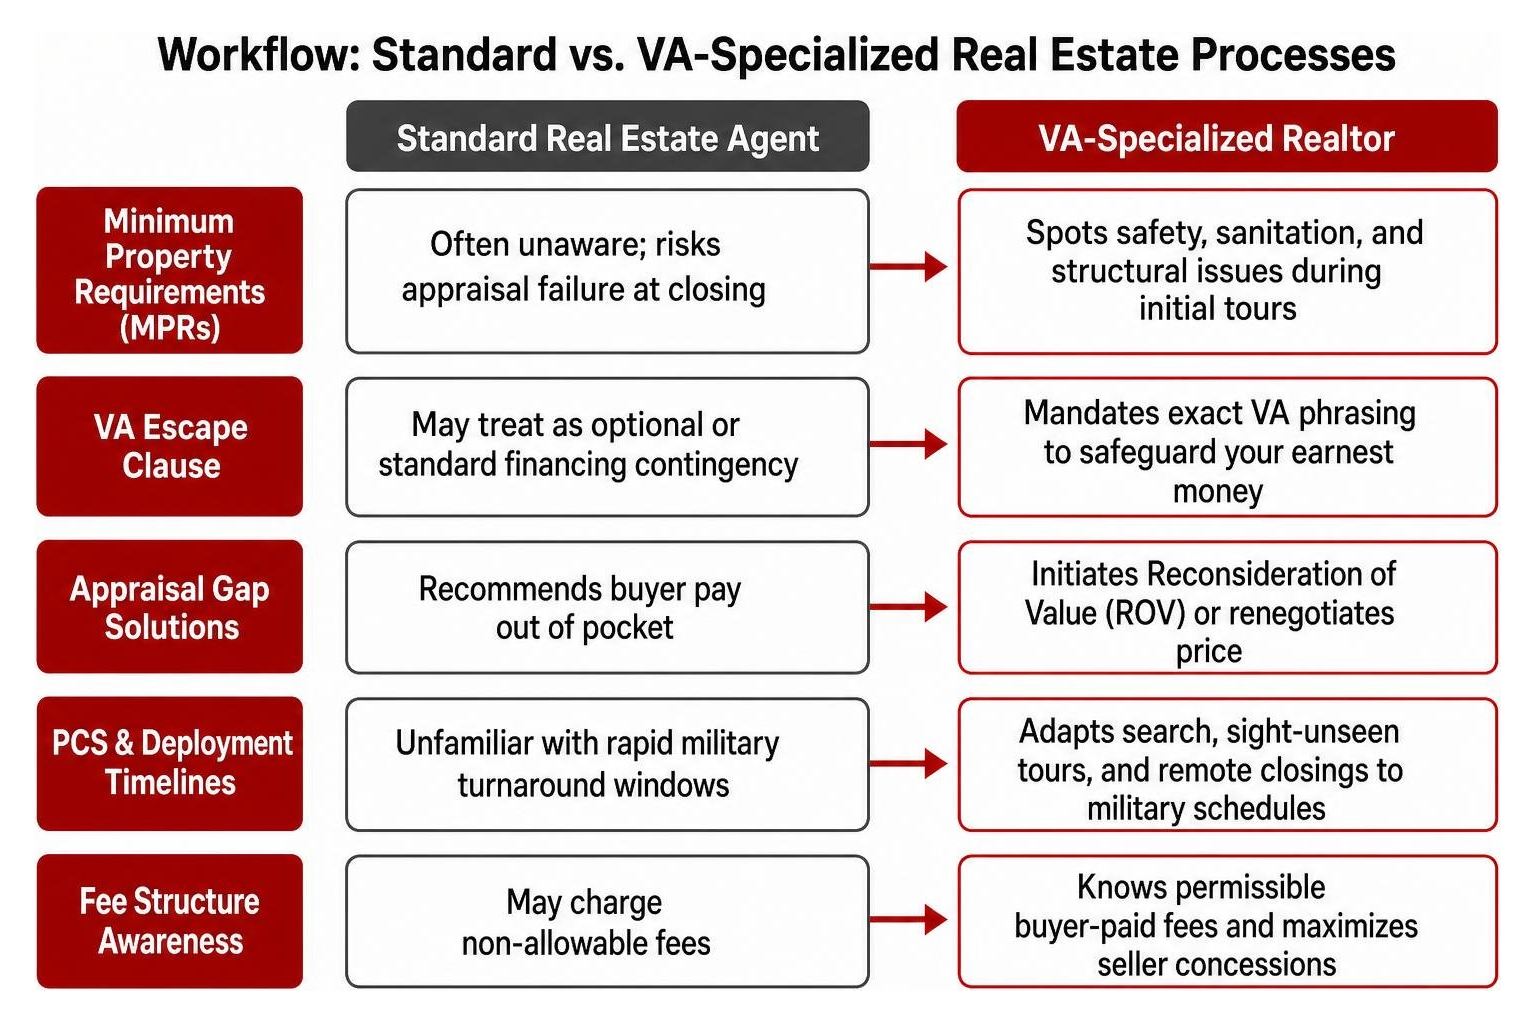
How VA Expertise Differs from Standard Real Estate Representation
The Department of Veterans Affairs sets specific standards to protect military buyers, which you can explore on the official VA Home Loans – Veterans Benefits Administration portal.
| Feature | Standard Real Estate Agent | VA-Specialized Realtor |
|---|---|---|
| Minimum Property Requirements (MPRs) | Often unaware; risks appraisal failure at closing | Spots safety, sanitation, and structural issues during initial tours |
| VA Escape Clause | May treat as optional or standard financing contingency | Mandates exact VA phrasing to safeguard your earnest money |
| Appraisal Gap Solutions | Recommends buyer pay out of pocket | Initiates Reconsideration of Value (ROV) or renegotiates price |
| PCS & Deployment Timelines | Unfamiliar with rapid military turnaround windows | Adapts search, sight-unseen tours, and remote closings to military schedules |
| Fee Structure Awareness | May charge non-allowable fees | Knows permissible buyer-paid fees and maximizes seller concessions |
5 Critical Steps To Finding The Best VA Home Realtor That Could Save You Thousands
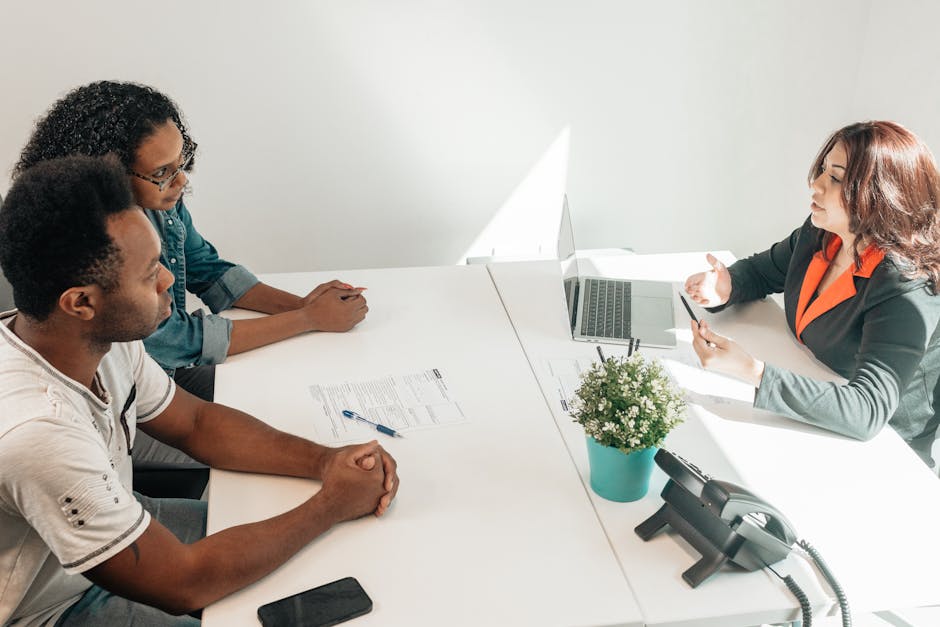
Selecting an agent should be approached like an official promotion board. As you review your guide to VA home loans, follow these five steps to ensure your agent protects both your family and your wallet.
Step 1: Verify Military and VA Transaction Experience
Do not settle for an agent who only handles one or two VA transactions a year. You need a dedicated professional who closes multiple military deals annually and understands the unique stress of Permanent Change of Station (PCS) orders. Look for agents holding specialized credentials, such as the Military Relocation Professional (MRP) certification, which signals baseline training in military benefits and rapid relocation timelines.
Step 2: Screen for Deep Knowledge of VA Appraisals and MPRs
The VA requires every home to satisfy strict Minimum Property Requirements (MPRs) ensuring safety, security, and structural soundness. A qualified realtor spots red flags—such as peeling paint on pre-1978 homes, inadequate heating systems, or dry rot—before you ever make an offer. If an appraisal comes in below the purchase price, a skilled agent knows how to file a formal Reconsideration of Value (ROV) with solid comparable sales rather than asking you to bridge the gap with personal cash.
Step 3: Conduct a Rigorous Realtor Interview with Targeted Questions
Never hire the first agent you meet without an interview. Prepare a structured list of questions:
- How many VA transactions did you successfully close over the past 12 months?
- What is your average list-to-sale price ratio for buyer clients?
- How do you structure communication if I am deployed, working shifts, or across different time zones?
- Can you provide references from two recent military or veteran clients?
Step 4: Evaluate Negotiation Strategy for Seller Concessions and Fees
Your agent must be aggressive when structuring your offer. Beyond asking for price cuts, they should know how to negotiate seller-paid closing costs. While lenders often charge a 1% origination fee alongside standard title and escrow charges, an expert agent pairs you with the best lenders for VA home loans and negotiates concessions to eliminate your upfront burden.
Step 5: Review Written Agreements and Military Rebate Options
Before signing a buyer-broker agreement, examine how the agent expects to be paid. Inquire about military homebuyer programs and rebates, such as cash-back incentives or commission rebates where permitted by state law. Ensure the representation agreement explicitly states that you are never on the hook for excessive commissions that exceed what the seller or listing broker provides.
Common Pitfalls When Selecting an Agent and How to Avoid Them
Rushing into an agreement can lead to common pitfalls. Generalist agents often advise clients to waive crucial protections, or they omit the VA escape clause to make an offer seem more appealing to a seller. Another risk is dual agency—where the same agent represents both the seller and you—creating an inherent conflict of interest when negotiating purchase prices and repair credits.
Before diving into house hunting, brush up on how to apply for a VA home loan in 5 easy steps so you know the requirements before visiting properties.
Applying The 5 Critical Steps To Finding The Best VA Home Realtor That Could Save You Thousands in 2026
Under VA Circular 26-24-14, veterans can negotiate and pay buyer-broker fees directly if a seller refuses to cover them. However, our goal is to ensure you never pay avoidable expenses. An experienced agent will negotiate seller-paid buyer representation or craft an offer where your net costs remain zero, protecting your liquid reserves while keeping your transaction fully compliant with current lending rules.
Frequently Asked Questions About Choosing a VA Realtor
Can a VA buyer pay their real estate agent’s commission directly?
Yes. Under updated VA policies, buyers using a VA loan can pay reasonable and customary buyer-broker fees if they choose to, provided the terms are established in a written agreement before touring homes. However, a top-tier agent will prioritize negotiating those costs into seller concessions.
How many VA transactions should a realtor close annually to be considered an expert?
Ideally, an agent should close at least 5 to 10 VA transactions per year. This volume ensures they stay current on local appraisal turn times, MPR guidelines, and effective negotiation strategies.
What is the VA escape clause and why must an agent include it?
The VA escape clause is a mandatory protection ensuring that you cannot be forced to complete a purchase or forfeit your earnest money deposit if the property’s appraised value comes in lower than the agreed-upon sales price.
Conclusion
Finding the right real estate agent is just as important as finding the right home. At USMilitary.com, we are committed to helping service members, veterans, and military families protect their financial well-being. By following these steps and partnering with true specialists, you can avoid costly appraisal delays, eliminate out-of-pocket closing fees, and build long-term wealth. Explore our full library of enlisted financial and servicemember benefits to make the most of your military service.
Free for Service Members & Veterans
Get the military benefits intel no one tells you about.
Weekly updates on VA benefits, pay changes, and money tips — free for service members and veterans.
No spam. Unsubscribe anytime. Your info is never shared.
Leave a Reply