| Question | Answer |
|---|---|
| Can a civilian assume a VA loan? | Yes, with lender and VA approval |
| Do you need military service? | No |
| What rate do you inherit? | The original loan’s rate (often 3% or lower) |
| Is there a funding fee? | Yes — just 0.5% of the remaining balance |
| Must it be a primary residence? | Yes |
| Does it affect the veteran seller? | Yes — their entitlement may be tied up |
Can a VA loan be assumed by a non veteran?
When we talk about a VA Assumable Loan, we are referring to a unique feature of the Department of Veterans Affairs home loan program. Unlike most conventional mortgages, which have “due-on-sale” clauses that require the loan to be paid in full when a house is sold, VA loans allow a new buyer to step into the original borrower’s shoes. For those wondering, “can a va loan be assumed by a non veteran,” the answer is a resounding yes. However, there are several “gatekeepers” involved in this process. First, the loan servicer (the company that collects the monthly payments) must approve the assumption. Most VA loans closed after March 1, 1988, require formal lender approval.
The buyer doesn’t need a military background, but they must meet the same credit and income standards as a Veteran. Additionally, the property must remain a primary residence. You cannot assume a VA loan to use the property as a vacation home or a rental right out of the gate. For more details on the official stance, you can visit VA.gov – VA Home Loan Assumptions.
VA Home Loan
See If You Qualify for a $0-Down VA Loan
Check your VA loan eligibility in a few minutes. It's free, with no obligation.
Financial Requirements and the Assumption Gap
Assuming a loan isn’t a “get out of jail free” card regarding financial scrutiny. Even though the buyer isn’t applying for a new loan, they are being underwritten to ensure they can handle the existing one.
The Credit and Income Bar
Lenders generally look for a credit score of at least 620, though some may have higher overlays. They will also analyze your Debt-to-Income (DTI) ratio, usually looking for 41% or lower, and ensure you meet the VA’s “residual income” requirements—the amount of money left over each month after all major bills are paid.Bridging the “Assumption Gap”
The biggest hurdle we see for non-veterans is the “assumption gap.” Imagine a home is selling for $500,000, but the Veteran seller only owes $350,000 on their mortgage. That $150,000 difference is the equity the seller has built up. As the buyer, you must cover that $150,000 at closing. This can be done via:- Cash: Most common, but requires significant liquidity.
- Secondary Financing: You can sometimes take out a second mortgage to cover the gap, provided the total debt still fits within the lender’s DTI limits and the second loan is subordinate to the VA loan.
The 0.5% Funding Fee and Closing Costs
One of the most attractive parts of an assumption is the cost savings. When you take out a new VA loan, the funding fee can range from 2.15% to 3.3% of the loan amount. With an assumption, that fee drops to a flat 0.5%.| Cost Category | New VA Purchase Loan | VA Loan Assumption |
|---|---|---|
| VA Funding Fee | 2.15% – 3.3% | 0.5% |
| Appraisal Fee | $600 – $1,200 | Usually Not Required |
| Origination Fee | Up to 1% | $0 (Processing fee only) |
| Servicer Processing Fee | N/A | Capped (approx. $300 + locality) |
Risks for the Veteran Seller: Entitlement and Liability
This is where we have to have a serious talk with our Veteran community. While the question “can a va loan be assumed by a non veteran” is answered with a “yes,” the consequences for the seller are significant.The Entitlement Trap
When a Veteran uses a VA loan, a portion of their “entitlement” is tied to that property. If another Veteran assumes the loan and has enough entitlement to “substitute” it, the original seller gets their full benefit back. However, if a non-veteran assumes the loan, the original Veteran’s entitlement stays tied to that house until the loan is paid off in full. This means the Veteran might not have enough entitlement left to buy another home with $0 down.Release of Liability
The seller must ensure they receive a formal Release of Liability from the VA or the servicer. Without this, if the non-veteran buyer defaults three years from now, the VA could still come after the Veteran for the debt, and it could destroy the Veteran’s credit. Before signing anything, sellers should review Form 26-10291 (the entitlement acknowledgment form) and check the VA.gov – Transfer of Ownership fact sheet. If you’re a Veteran looking to move but keep your benefit, you might want to ask: Can You Refinance a VA Loan instead of selling via assumption?The Step-by-Step Process for Non-Veterans
Qualification requirements: Can a VA loan be assumed by a non veteran?
To successfully assume a loan, the civilian buyer must prove they are just as “safe” a bet as a military member. We look at three main pillars:- Creditworthiness: A solid history of on-time payments.
- Residual Income: VA standards require that after you pay your mortgage and all other monthly debts, you have a specific amount of cash left for food, gas, and clothes based on your family size and region.
- Occupancy Intent: You must sign a document stating you intend to live in the home as your primary residence.
Timeline and paperwork: Can a VA loan be assumed by a non veteran?
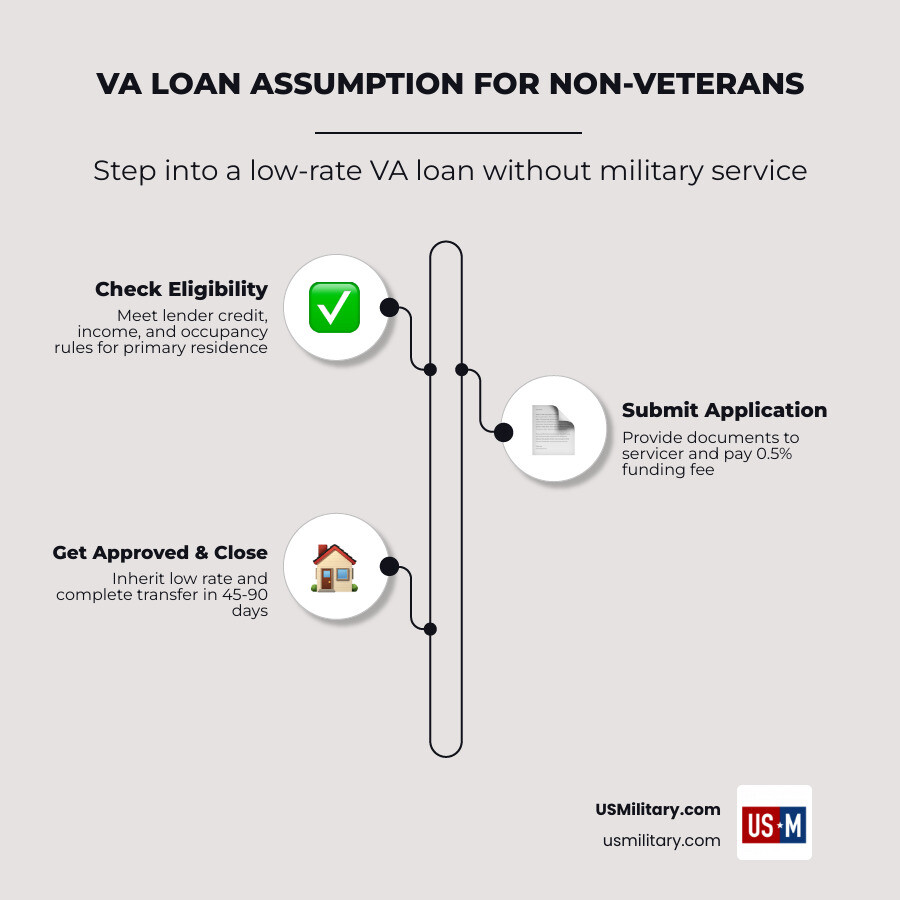
Don’t expect to close in 30 days. Because the mortgage servicer doesn’t make much money on an assumption (they only get that $300 fee), these files often sit at the bottom of the stack. The process typically takes 45 to 90 days.- Step 1: The seller contacts their servicer to request an “Assumption Package.”
- Step 2: The buyer completes the application and provides pay stubs, W-2s, and bank statements.
- Step 3: The servicer’s underwriting department reviews the file.
- Step 4: Once approved, the VA issues the Release of Liability and the 0.5% funding fee is paid.
VA Home Loan
See If You Qualify for a $0-Down VA Loan
Check your VA loan eligibility in a few minutes. It's free, with no obligation.
Frequently Asked Questions
Can a non-veteran assume a VA loan and then rent it out?
Not immediately. The VA requires the person assuming the loan to certify that they intend to occupy the home as their primary residence. If you assume the loan with the intent to immediately turn it into an investment property, that could be considered mortgage fraud. However, if you live in the home for a year or two and then your life circumstances change, you may be able to rent it out at that point, similar to standard VA loan rules.What happens if the non-veteran buyer defaults on the assumed loan?
If the Veteran seller obtained a formal Release of Liability, they are protected. The VA will handle the foreclosure with the new owner, and the Veteran’s credit will remain intact. However, if the Veteran did not get that release, they are still legally responsible for the mortgage. Furthermore, if the buyer defaults, the Veteran’s entitlement remains “charged” or lost until the VA is made whole.How long does the VA loan assumption process take in 2026?
As of May 2026, most assumptions are taking between 60 and 90 days. While the VA has issued circulars encouraging servicers to process these within 45 days, the reality of high volume and limited servicer staffing often pushes the timeline back. We always recommend building a 90-day window into your purchase contract to be safe.Conclusion
At USMilitary.com, we believe that the VA loan is the greatest thank-you a nation can give its defenders. While can a va loan be assumed by a non veteran is a clear “yes,” it is a strategy that requires caution, especially for the Veteran. For the civilian buyer, it is a chance to secure a 3% or 4% interest rate in a world of 7% averages—a move that could save you over $200,000 in interest over the life of the loan. For the Veteran, it’s a way to sell a home faster or for a premium price, provided you understand the impact on your future benefits. If you’re ready to explore your options, we recommend starting with our list of the Best 10 VA Home Loan Lenders to find professionals who understand the nuances of the assumption process. Whether you are serving, have served, or are a civilian looking to buy from a hero, we are here to provide the resources you need to make the best financial decision for your family.Free for Service Members & Veterans
Get the military benefits intel no one tells you about.
Weekly updates on VA benefits, pay changes, and money tips — free for service members and veterans.
No spam. Unsubscribe anytime. Your info is never shared.