The top 10 personal loan lenders for military veterans are:
| Rank | Lender | Best For | APR Range | Max Loan |
|---|---|---|---|---|
| 1 | PenFed Credit Union | Best overall | 6.74% – 17.99% | $50,000 |
| 2 | Navy Federal Credit Union | Good credit | 8.99% – 18.00% | $50,000 |
| 3 | USAA | Large loans | 10.34% – 18.51% | $100,000 |
| 4 | LightStream | Excellent credit | 6.49% – 24.89% | $100,000 |
| 5 | Discover | Disabilities/medical | 7.99% – 24.99% | $40,000 |
| 6 | U.S. Bank | Fair credit | 8.74% – 24.99% | $50,000 |
| 7 | First Tech Federal CU | Bad credit | 6.99% – 18.00% | $50,000 |
| 8 | SoFi | Large amounts fast | 8.99% – 29.99% | $100,000 |
| 9 | Upgrade | Fair credit online | 7.74% – 35.99% | $50,000 |
| 10 | Upstart | No/low credit score | 6.70% – 35.99% | $75,000 |
As a veteran, you have real options when you need cash fast — whether it’s for debt consolidation, emergency expenses, or a PCS move. But the landscape can be confusing and, frankly, full of misleading claims.
One important thing to clear up right away: the VA does not offer personal loans. Any lender advertising a “VA personal loan” should raise a red flag. The VA focuses on housing and other benefits — not unsecured personal lending. That means veterans turn to private lenders, and not all of them have your best interests in mind.
Personal loans for veterans are unsecured installment loans — no collateral required. You borrow a fixed amount, repay it in fixed monthly payments over a set term, and pay interest on the balance. Simple in theory. The challenge is finding a lender with fair rates, no hidden fees, and terms that work for your budget.
This guide cuts through the noise and gives you a clear, honest look at your best options.
I’m Larry Fowler, publisher of the USMilitary.com Network since 2007 and a trusted resource for veterans navigating benefits, financial decisions, and military life. My experience connecting service members with reliable financial information makes me well-positioned to walk you through the top 10 personal loan lenders for military veterans and help you borrow smart. Let’s get into the details so you can make a confident, informed decision.
Top 10 personal loan lenders for military veterans terms to remember:
Understanding Military Protections and Loan Basics
When we talk about borrowing money as a veteran, we have to look at the legal safety net designed to keep you from falling into predatory debt traps. Two major laws provide these protections: the Military Lending Act (MLA) and the Servicemembers Civil Relief Act (SCRA).
The Military Lending Act (MLA) is a powerhouse for active-duty members and their dependents. It caps the Military Annual Percentage Rate (MAPR) at 36%. This is critical because many “quick cash” or payday lenders often charge 400% or more. The MLA also prohibits prepayment penalties—meaning you can pay your loan off early without being punished—and bans mandatory arbitration clauses that would limit your right to go to court. While the MLA primarily covers active-duty personnel, many of the top 10 personal loan lenders for military veterans extend similar fair-lending practices to veterans as a matter of policy.
The Servicemembers Civil Relief Act (SCRA) is slightly different. It allows those entering active duty to cap interest rates at 6% on loans they took out before they started their service. If you are a veteran returning to active duty, this is a benefit you must request in writing from your lender.
Does the VA Offer Personal Loans?
We get this question daily: “Can I get a personal loan through the VA?” The short answer is no. The Department of Veterans Affairs does not issue personal loans for general use. Their mission is focused on housing, healthcare, and education.
If you see an advertisement for a “VA Personal Loan,” be skeptical. These are almost always private lenders using the VA name to get your attention. Instead of a government check, you will be working with private credit unions or banks. However, you can explore Veteran Home Loan Rates/ if you are looking to tap into your home’s equity, which is a different financial tool altogether.
How Personal Loans Differ from VA Home Loans
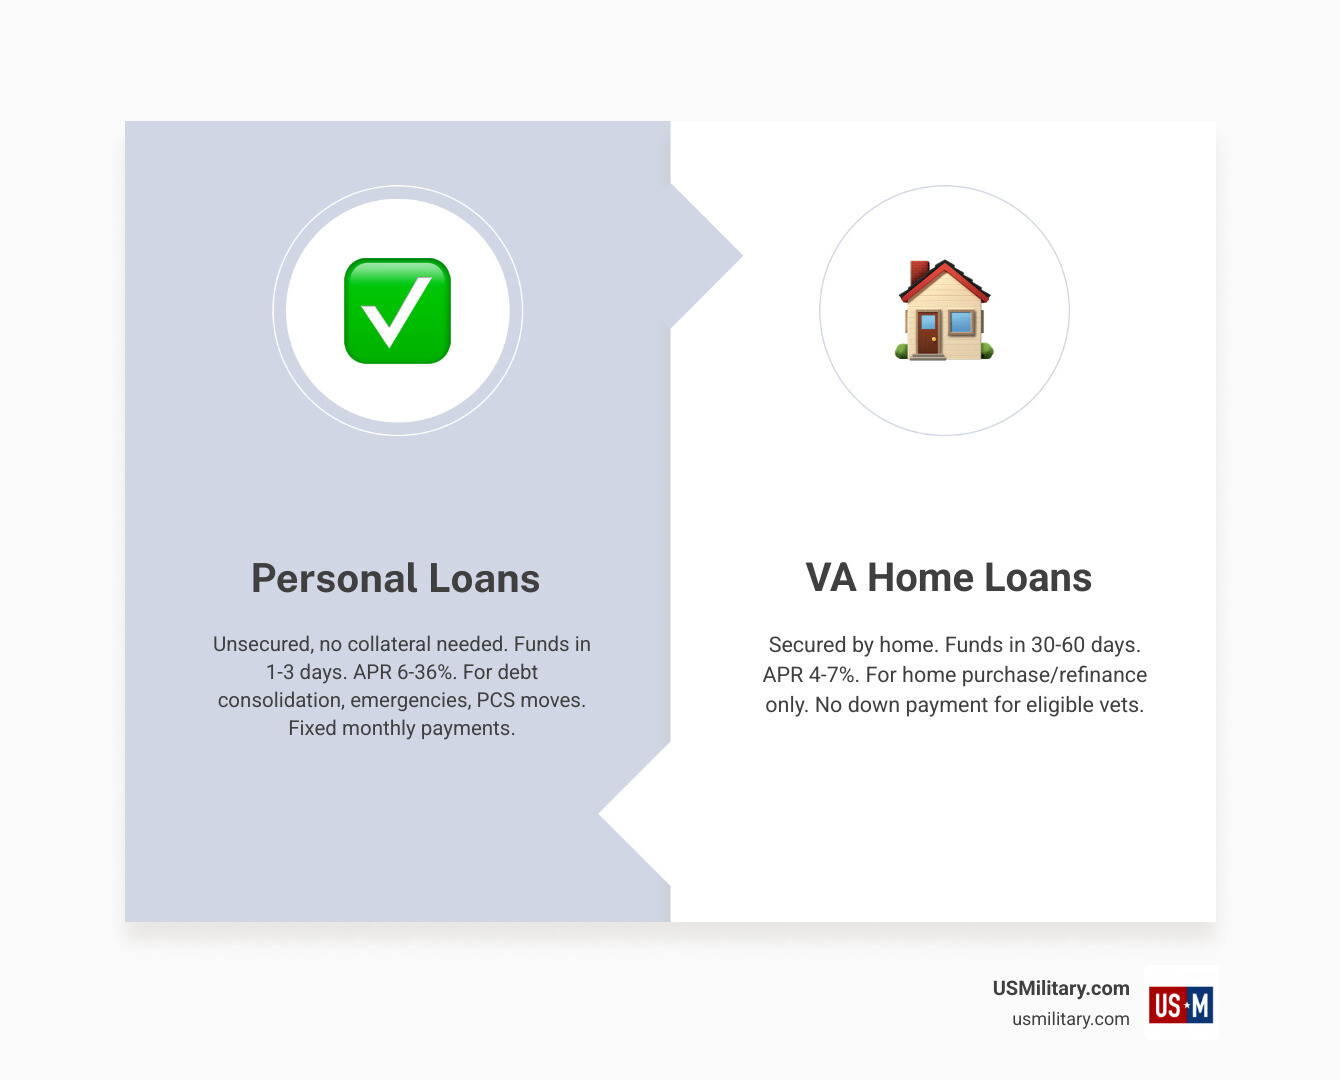
It is easy to get these confused, but they serve very different purposes. A Va Home Loan/ is a secured loan, meaning the home itself is collateral. If you don’t pay, the lender can take the house. Because of this security, home loans usually have much lower interest rates and allow you to borrow hundreds of thousands of dollars.
A personal loan is typically unsecured. There is no collateral. Because the lender is taking a bigger risk, the interest rates are higher than a mortgage but usually much lower than a credit card. The biggest advantage? Speed. While a VA home loan can take 30 to 45 days to close, a personal loan from one of our top lenders can often be in your bank account within 24 to 48 hours.
| Feature | Personal Loan | VA Home Loan |
|---|---|---|
| Collateral | None (Unsecured) | The Home (Secured) |
| Approval Time | 1–3 Days | 30–50 Days |
| Max Amount | Up to $100,000 | Varies (No limit with full entitlement) |
| Common Use | Debt consolidation, repairs, moving | Buying or refinancing a home |
Knowing these Va Home Loan Benefits/ helps you decide if you should borrow against your house or simply take out a quick installment loan.
Top 10 Personal Loan Lenders for Military Veterans in 2026
Finding the right lender is about more than just the lowest rate; it’s about finding a partner that understands the military lifestyle. Whether you are dealing with a sudden medical bill or a Permanent Change of Station (PCS) move, these lenders have been vetted for their transparency and veteran-friendly terms.

Comparing the Top 10 Personal Loan Lenders for Military Veterans
Let’s explore the specifics of why these institutions made our list for 2026.
1. PenFed Credit Union (Best Overall) PenFed is a powerhouse in the veteran community. They offer loans from $500 to $50,000 with APRs starting as low as 6.74%. What we love most? No origination fees. They have provided over $50 million in financial support through their foundation, proving they give back to the community they serve.
- Terms: 12 – 60 months.
- Best For: Veterans who want a no-fee, straightforward experience.
2. Navy Federal Credit Union (Best for Good Credit) Membership is open to all branches, and their personal loans are highly competitive. With rates starting at 8.99% and terms up to 60 months (or longer for home improvements), they are a go-to for many. They also offer a 0.25% interest rate discount for active duty and retired military members on certain products.
- Max Loan: $50,000.
- Best For: Existing members who value a relationship-based lender.
3. USAA (Best for Large Loans) USAA is legendary for its service to the military. They offer personal loans up to $100,000 with terms up to 84 months. While their starting APR (10.34%) is slightly higher than PenFed, their ability to handle large amounts and offer a 0.25% autopay discount makes them a top contender.
- Eligible: Honorably discharged veterans and their families.
- Best For: Large-scale debt consolidation.
4. LightStream (Best for Excellent Credit) If your credit score is 700 or higher, LightStream is hard to beat. They offer some of the lowest rates in the industry (starting at 6.49% with autopay) and can fund loans up to $100,000. They are known for their “Rate Beat” program and a completely paperless process.
- Terms: 24 – 144 months.
- Best For: Veterans with stellar credit history.
5. Discover (Best for Medical/Disability Expenses) Discover is unique because they offer specific support for veterans dealing with medical expenses. Their loans range from $2,500 to $40,000 with no origination or prepayment fees.
- Min Credit: Reportedly 660.
- Best For: Managing healthcare costs or home accessibility modifications.
6. U.S. Bank (Best for Fair Credit) Not every veteran has a perfect 800 credit score. U.S. Bank offers accessible loans for those in the 680 range. They provide loans up to $50,000 with no hidden fees and a quick digital application.
- APR: 8.74% – 24.99%.
- Best For: Veterans with “good but not great” credit.
7. First Tech Federal Credit Union (Best for Bad Credit) First Tech is often more lenient than big banks. They offer small-dollar loans starting at $500, which is great for avoiding payday lenders. Their rates top out at 18.00%, which is very reasonable for lower-credit borrowers.
- Loan Range: $500 – $50,000.
- Best For: Rebuilding credit or small emergencies.
8. SoFi (Best for Fast Funding) SoFi is a modern lender that offers loans up to $100,000 with no fees. They are famous for their “member benefits,” which include career coaching and financial planning.
- Funding Speed: Often same-day if approved by 5:30 p.m. ET.
- Best For: Tech-savvy veterans who need money yesterday.
9. Upgrade (Best Online Experience) Upgrade is great for fair credit (580+) and offers a very transparent online platform. They do charge origination fees (1.99% – 9.99%), so factor that into your total cost.
- APR: 7.74% – 35.99%.
- Best For: Quick online comparison and fair credit approval.
10. Upstart (Best for No Credit History) Upstart uses AI to look at more than just your credit score—they consider your education and work history. This is perfect for younger veterans who may not have built up a long credit file yet.
- Max Loan: $75,000.
- Best For: Recent separates with limited credit history.
For more details on these options, you can check the 5 Best Personal Loans for Veterans [April 2026] list for real-time updates.
Eligibility for the Top 10 Personal Loan Lenders for Military Veterans
To qualify for the best rates among the top 10 personal loan lenders for military veterans, you generally need:
- Proof of Service: Usually a DD-214 or a Statement of Service.
- Income Verification: Pay stubs, tax returns, or VA disability award letters. Most lenders accept disability income as a valid source of repayment.
- Credit Score: While some lenders like Upstart or First Tech are flexible, the best rates usually require a score of 680 or higher.
- Debt-to-Income (DTI) Ratio: Lenders prefer a DTI below 36%. This means your total monthly debt payments shouldn’t exceed 36% of your gross monthly income.
If you are a veteran looking for more permanent housing solutions, you can also research Military Home Loans/ to see how your eligibility differs for secured debt.
How to Apply and Compare Veteran Loan Offers
Applying for a loan shouldn’t be a “shot in the dark.” The smartest way to start is through prequalification. Most of the top 10 personal loan lenders for military veterans allow you to see your estimated rate with a “soft pull” on your credit. This does not hurt your credit score.
- Check Your Credit: Use a free service to see where you stand. If you see errors, dispute them before applying.
- Prequalify with 3-4 Lenders: Compare the APR, not just the interest rate. The APR includes fees like origination charges.
- Gather Your Documents: Have your DD-214, recent bank statements, and proof of income ready.
- Read the Fine Print: Look for prepayment penalties. None of the top 10 lenders listed above charge them, but other lenders might.
- Apply Formally: Once you pick the best offer, you’ll submit a formal application. This will trigger a “hard pull,” which may temporarily dip your credit score by a few points.
For a deeper dive into the application process, Best Personal Loans for Veterans in 2026 – NerdWallet offers excellent step-by-step checklists.
Red Flags of Predatory Lenders
Veterans are often targets for unscrupulous lenders. Watch out for these warning signs:
- Guaranteed Approval: No legitimate lender can guarantee approval without looking at your finances.
- No Credit Check: These loans almost always come with triple-digit interest rates.
- Pressure Tactics: If a lender tells you the offer expires in an hour, walk away.
- Upfront Fees: You should never have to pay money to “process” your application before receiving the loan.
Staying safe also means protecting your other assets. You can find Highly Affordable Home And Auto Insurance Rates For Us Military Veterans/ to ensure your financial house is in order while you manage your debt.
Alternatives to Personal Loans for Veterans
Before you take on new debt, check if you qualify for assistance that doesn’t need to be paid back.
- VFW Unmet Needs Grants: Provides up to $2,500 for financial hardships related to military service.
- USA Cares: Offers emergency assistance for post-9/11 veterans to prevent evictions or utility shut-offs.
- VA Life Insurance Loans: If you have a permanent VA life insurance policy (like VGLI), you may be able to borrow against the cash value at very low rates. Note: This does not apply to the newer VALife program.
- Military Aid Societies: Organizations like Army Emergency Relief or the Navy-Marine Corps Relief Society often provide zero-interest loans or grants for active duty and some retirees.
If your goal is specifically to buy your first home, a First Time Home Buyer Va Loan/ is almost always a better financial move than a personal loan.
Frequently Asked Questions
Can I get a personal loan with a 600 credit score?
Yes, but it will be more expensive. Lenders like Upgrade and Upstart specialize in fair-to-poor credit. You may also want to look into “secured” personal loans, where you use a savings account or vehicle title as collateral to lower the interest rate.
How does the Military Lending Act protect veterans?
While the MLA primarily covers active-duty members (capping rates at 36%), its influence has forced many lenders to adopt more transparent practices for veterans as well. It ensures you aren’t charged hidden fees that could push your effective interest rate into the triple digits.
Are there specific loans for disabled veterans?
Yes. Lenders like Discover and USAA are very familiar with VA disability income. Additionally, some states offer specific low-interest loan programs for veterans with a certain disability rating. Always include your disability compensation as “non-taxable income” on your application—it can actually help you qualify for a larger amount.
Conclusion
Navigating personal finance doesn’t have to be a solo mission. At USMilitary.com, we are committed to providing you with the intel you need to make the best decisions for your family. Whether you are using one of the top 10 personal loan lenders for military veterans to consolidate high-interest credit card debt or to cover an unexpected car repair, the key is to borrow only what you need and have a clear plan for repayment.
A personal loan is a tool—not a permanent solution. Use it wisely, avoid predatory lenders, and always look for grants or military-specific aid first. If you’re still curious about other borrowing options, don’t forget to ask: What is a VA Loan? and see how it fits into your long-term financial strategy. Stay disciplined, stay informed, and thank you for your service.
Free for Service Members & Veterans
Get the military benefits intel no one tells you about.
Weekly updates on VA benefits, pay changes, and money tips — free for service members and veterans.
No spam. Unsubscribe anytime. Your info is never shared.